Disclosure: this page contains affiliate links for travel services (not hospitals). We may earn a commission at no extra cost to you.
By KMedTrip editorial · Updated · Written with AI assistance · Reviewed by KMedTrip native-speaker review team
This guide is general information, not medical advice. KMedTrip is run by a government-registered foreign patient facilitator (an agency that helps international patients arrange medical care). We do not recommend, rank or receive payment from any hospital or clinic.
Important: Standard travel insurance usually does not cover elective or cosmetic procedures. “Elective” means planned and chosen by you, not an emergency. It usually does not cover complications (new health problems caused by the procedure) either. That includes:
Do not assume you are covered. Read your own policy and ask your insurer in writing. Insurance rules and products differ from country to country, so the answer depends on where you live and which policy you hold.
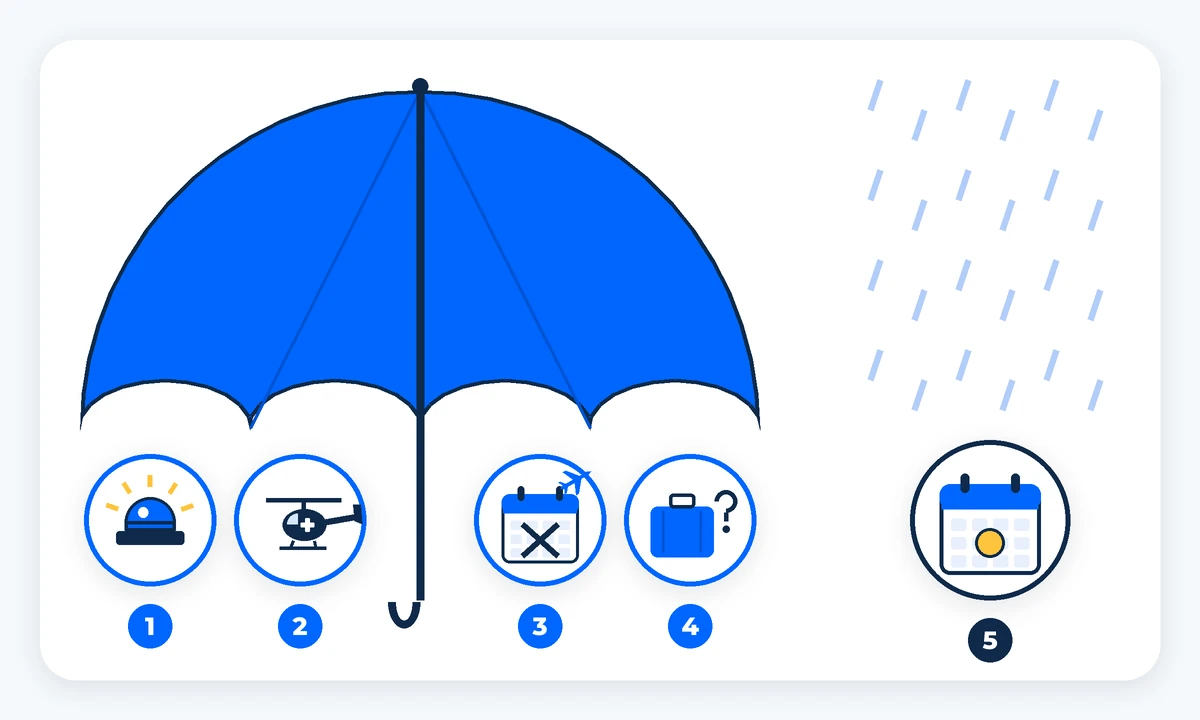
Figure 1. What a typical travel policy is built for, and what sits outside it. ① Emergency treatment for a new illness or injury. ② Emergency evacuation or repatriation. ③ Trip cancellation or interruption. ④ Lost, delayed or stolen luggage. ⑤ A planned procedure: outside the basic idea of travel insurance.
Travel insurance is designed for sudden, unplanned problems while you are away. Typical policies cover things like:
The key word is emergency. The policy pays for things you did not plan. A procedure you booked in advance sits outside the basic idea of travel insurance.
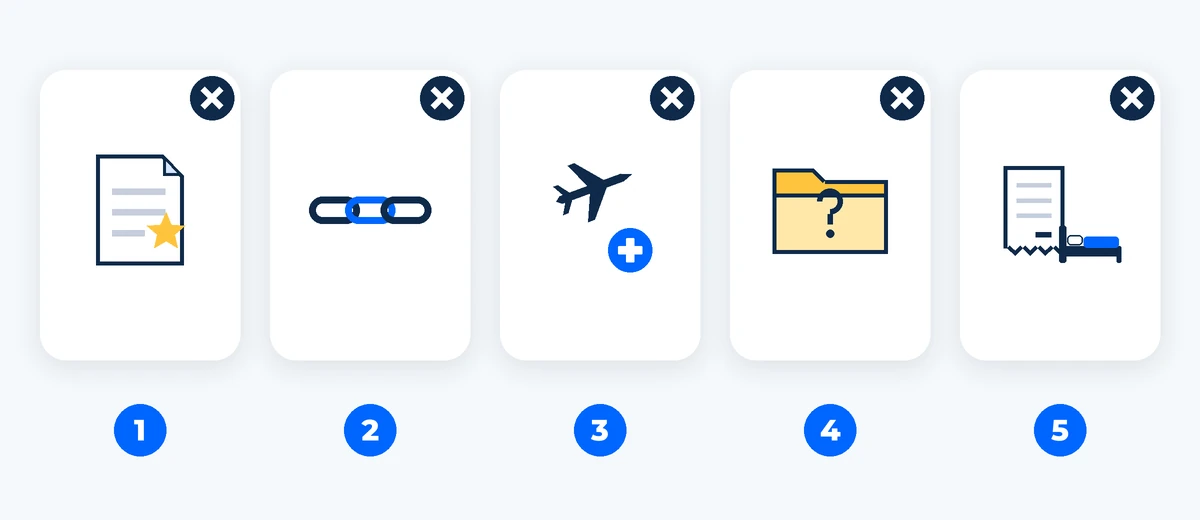
Figure 2. Five common exclusions (things a policy does not pay for). ① Cosmetic or elective treatment. ② Complications of excluded treatment. ③ Traveling to get treatment. ④ Undeclared pre-existing conditions. ⑤ Extra stay and travel costs.
Policy wording differs between insurers and countries. But these exclusions are common:
| Exclusion | What it means in plain words |
|---|---|
| Cosmetic or elective treatment | Procedures for appearance, or treatment that is not medically necessary, are usually not paid. |
| Complications of excluded treatment | If the first procedure is not covered, problems from it (infection, bleeding, a revision) are usually not covered either. |
| Traveling to get treatment | If the purpose of the trip is treatment, many policies cut cover. This can affect all your medical cover, not only the procedure. |
| Undeclared pre-existing conditions | A health problem you already had and did not tell the insurer about. |
| Extra stay and travel costs | Hotel nights or a new flight home caused by a non-covered procedure. |
A real example: one travel insurer’s published exclusion list excludes procedures done for cosmetic or aesthetic reasons. It also excludes complications that come from services it does not cover (SafetyWing exclusion list, accessed Oct 2026).
UK government travel advice says most travel insurance policies will be invalidated (made void) by planned treatment abroad. It says you will likely need specialist cover (Travel Aware, accessed Oct 2026). The NHS also warns that standard travel insurance typically does not cover surgical complications (NHS, accessed Oct 2026).
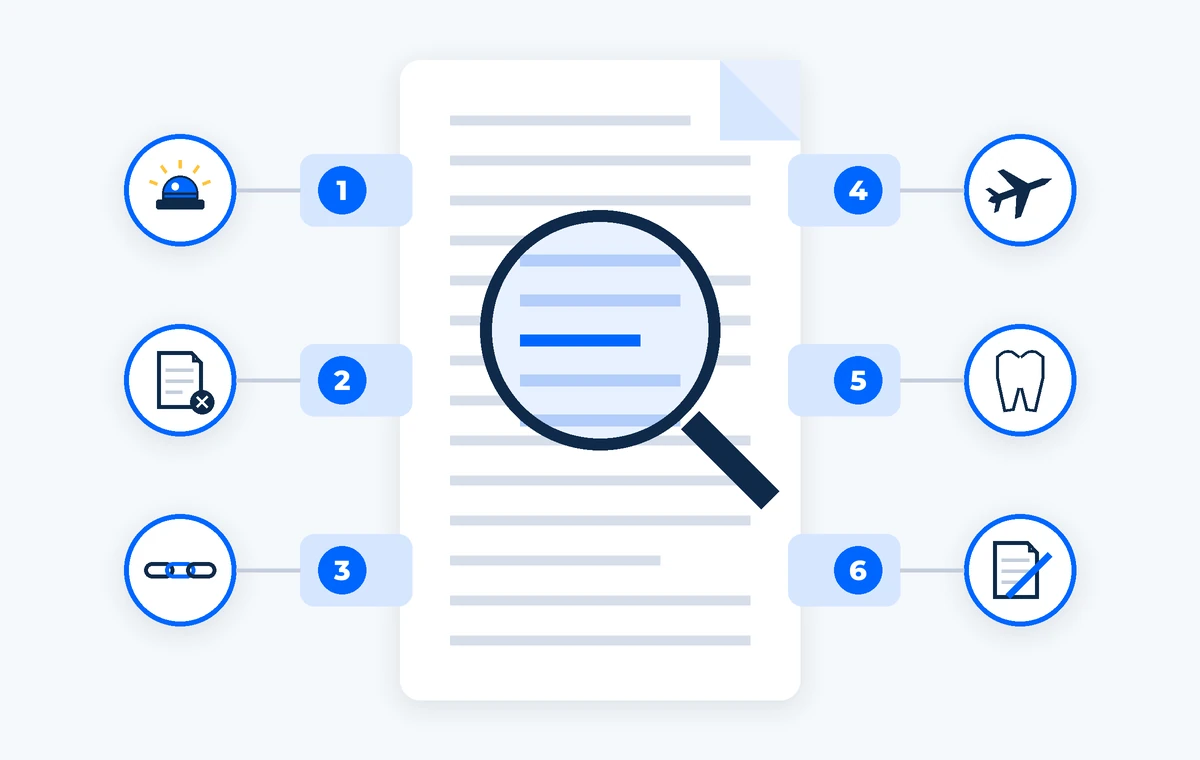
Figure 3. Six parts of the policy document to read before you buy. ① Definition of medical emergency. ② List of exclusions. ③ Complications clause. ④ Purpose-of-trip rules. ⑤ Dental limits. ⑥ Declaration duties.
Do not rely on a summary page or an advert. Read the full policy document. It is often called the “policy wording” or “certificate”.
How to do it, step by step:
| Section to find | Words to search | What to look for |
|---|---|---|
| ① Definition of “medical emergency” | emergency, unforeseen, sudden | Planned treatment rarely fits this definition. |
| ② List of exclusions | cosmetic, elective, aesthetic, plastic surgery, dental | Whether your procedure is named. |
| ③ Complications clause | complication, arising from | Whether problems from excluded treatment are also excluded. |
| ④ Purpose-of-trip rules | purpose of travel, traveling for treatment | Whether cover is reduced or canceled when you travel for treatment. |
| ⑤ Dental limits | dental, emergency dental | Emergency dental pain relief may have a small limit. Planned dental work is usually excluded. |
| ⑥ Declaration duties | declare, disclose | Whether you must tell the insurer about planned treatment. Not doing so can void the policy. |
Insurers take different amounts of time to answer emails. Start this check early, before you pay any deposit. A phone answer is hard to rely on later, so always ask for the answer by email.
Your options depend on where you live and which companies sell insurance there. Things you can ask about:
Questions you can copy into your email to the insurer:
If you buy a general travel insurance policy, treat it as cover for travel problems only. Do not count on it to pay for your procedure, its complications, extra recovery time or a later flight home. Plan your budget for these risks separately.
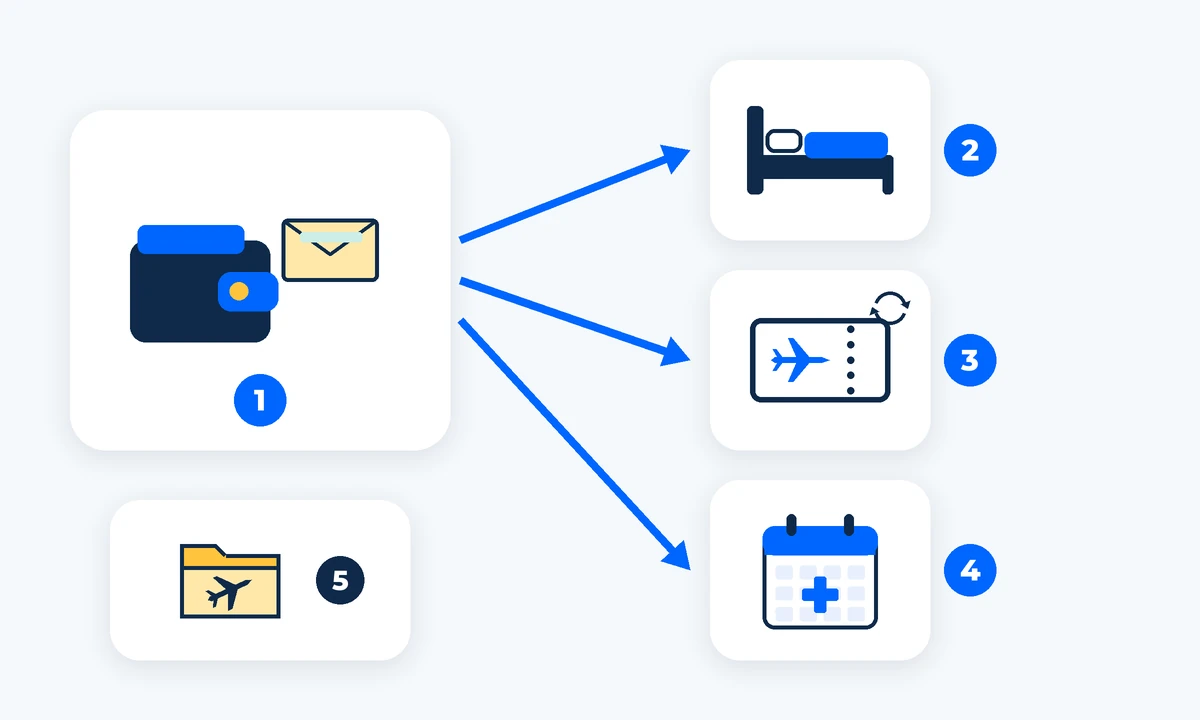
Figure 4. How to plan for complication costs that insurance usually will not pay. ① Emergency budget. ② Extra nights of accommodation. ③ A changed flight. ④ Extra clinic visits. ⑤ Copies of your medical records before flying home.
Because insurance will often not help, it is wise to:
Does travel insurance cover cosmetic surgery in Korea? Usually no. Standard travel insurance usually excludes elective and cosmetic procedures. It usually excludes their complications too.
If I get an infection after my procedure, will my travel insurance pay? Usually not. Complications of a procedure that is not covered are usually not covered either. Check the complications clause in your policy.
Is it still worth buying travel insurance? It can be, for travel problems like lost luggage or an unrelated accident. But first confirm in writing that the policy does not cancel your cover because your trip is for treatment.
What is “specialist” medical-travel cover? It is insurance sold for planned treatment abroad. It has its own limits and exclusions. Read the full wording before you buy.
Do I have to tell my insurer about my planned procedure? Many policies have declaration duties (rules about what you must tell them). Not telling the insurer can void the policy. Ask the insurer by email.
What else should I prepare? See our pre-departure checklist and sample itineraries. Both include buffer days for slower recovery.
If you’d like help planning, you can talk to a coordinator.